If you've quoted ISO-NE load this year, you've likely noticed fixed prices running hotter than the forward curve alone would explain, and a new acronym showing up in nearly every supplier's pricing notes: DASI. After its first full winter live in the market, DASI helped push ISO-NE wholesale costs to roughly $6.5 billion, the most expensive winter New England has recorded since its markets began in 2000.
Here's what DASI actually changed, why it moved fixed pricing more than the headline energy price suggests, how suppliers are handling the exposure, and what reforms are already underway to bring it back down.
What DASI Actually Changed
Every hour, ISO-NE has to keep supply equal to demand and hold enough backup capacity, called reserves, to absorb a sudden spike in load or the loss of a generator. Before March 2025, part of that need was covered through the Forward Reserve Market, which set prices months ahead, with the rest handled through out-of-market procurements.
DASI retired that structure and folded reserve procurement into the day-ahead market, so energy and reserves now clear together the day before delivery. As part of this new market mechanism, Energy Imbalance Reserves (EIR) were introduced as a call option that pays generators up front to hold capacity above their day-ahead schedule, in case day-ahead energy alone doesn't meet ISO-NE's load forecast (also known as the Forecast Energy Requirement, or FER). When it doesn't, the market procures EIR cheapest-first until the gap closes, and the last offer needed sets the price (FERP).
The result is that retailers are now responsible for costs associated with ISO-wide under-scheduling in the day-ahead market. These costs can be highly volatile, as seen this past winter.
The Winter That Made It Real
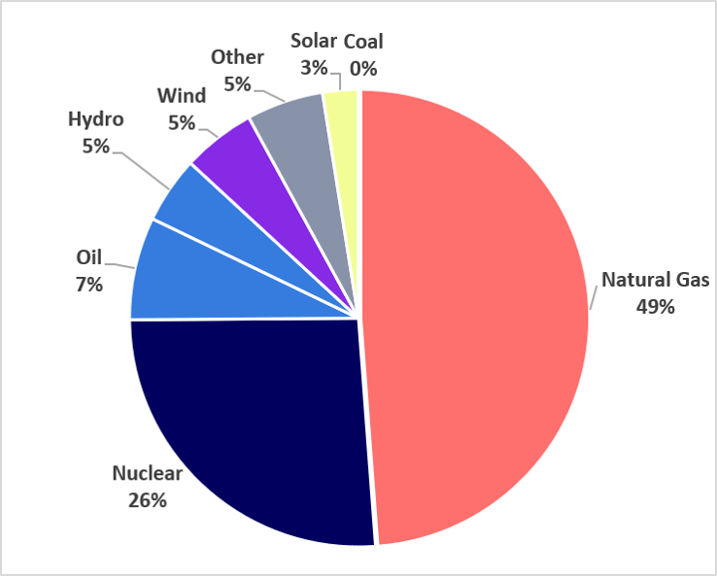
New England's reliance on natural gas and constrained pipeline capacity, mainly the Algonquin system, which carries roughly 60 to 65% of the region's delivered dry gas, made the 2025-2026 winter a live stress test for DASI. Widely described as the coldest winter New England has seen in two decades, it pushed heating demand hard enough against pipeline capacity that the grid leaned heavily on oil-fired generation to stay reliable, with regional gas prices briefly exceeding $120/MMBtu during the late-January cold snap.
On January 27 specifically, a storm pushed ISO-NE's forecast into territory only reachable with very expensive generation. Every added megawatt needed to hit the forecast pushed the FERP higher. Every load-serving entity picked up its share based on load ratio, which is the bill that eventually shows up in supply costs.
Why Fixed Quotes Moved More Than the Spot Curve
This is the part that matters most when you talk to customers. A true fixed-price contract locks in one number for the full term, which means a supplier pricing a fixed quote has to fold its best estimate of DASI-related risk, including the tail risk of another January 27, into the price at signing. That's a meaningfully different exposure than the day-ahead energy price alone, and it's a big part of why fixed quotes across the market moved more than spot prices suggest on their own: the quote is pricing a year, two, or three years of exposure to FERP spikes, not just today's curve.
It also means a supplier who underprices that risk to win a deal is taking on real loss exposure if the next stress event occurs within the contract term. This is worth keeping in mind when a quote looks unusually aggressive relative to the rest of the market.
How Suppliers Are Treating DASI Risk
Suppliers are generally taking one of two approaches to that exposure:
| Option 1: Bundled Into the Fixed Price | Option 2: Ancillary Costs Passed Through | |
| Description | The supplier absorbs DASI volatility and folds the risk directly into the quoted rate. | Some or all DASI-related costs stay variable and are billed separately, trued up against actual EIR/FERP settlement. |
| Benefit | Full price certainty for the term: the customer's number doesn't move regardless of how the market behaves. | Tighter starting price, since the supplier isn't pricing in a large risk premium up front. |
| Tradeoff | The supplier prices in a premium for the uncertainty, and the customer gives up any upside if DASI costs come in lower than feared. |
The customer carries real exposure to the next stress event, and the monthly number becomes harder to budget against. |
| Ask the supplier | How much of the DASI risk premium is baked in, and how it was estimated. |
How the pass-through is calculated and trued up, and whether there's a cap. |
What's Changing, and When
Four reforms are moving through ISO-NE's stakeholder process, and we're tracking each one closely. We'll flag it here as soon as either pending reform gets an implementation date.
- Non-Performance Factor (NPF) reduction: Approved and already in effect as of May 1, 2026, cutting the multiplier used to set reserve requirements from 120% to 115%. Modestly lowers FRS demand across all three reserve tiers.
- FER demand quantity adjustment: Approved June 18, 2026; implementation date still to be determined. Credits expected front-of-meter wind and solar output when setting the FER constraint, so the market stops committing generation to cover load renewables will already serve. Together with the NPF reduction, ISO-NE estimates that this change cuts DASI’s costs by roughly 28%.
- Strike price floor: Also approved June 18, 2026, implementation TBD. Ties the strike price to the marginal cost of an efficient distillate-fired combustion turbine, aimed squarely at preventing the kind of closeout blowout seen in January. Combined with the above, modeled savings reach 30%.
- GMM forecasting improvements: An ongoing workstream to get ISO-NE's real-time price forecasting model closer to actual settlement, narrowing the gap the strike price has to guess at.
On the highest-cost days, like January 2026, ISO-NE estimates the combined package would cut costs by about 35%.
What This Means for Evaluating Quotes
DASI is already baked into every ISO-NE quote you're assessing, but it rarely shows up as a line item, which makes it difficult to compare apples-to-apples across different suppliers. For clarity, ask your supplier:
- What DASI cost per MWh is assumed in each contract year, and does it change between year one and year three?
- Is the assumption built on an average winter or a stress case like January 2026?
- Is any DASI exposure carved out through a change-in-law or pass-through clause that could reprice the contract mid-term?
For the end-use customer, the risk isn't a higher bill under a fixed rate. It's counterparty risk: a mid-term repricing request, a change-in-law claim, or, in the worst case, a supplier exit that moves the account to default utility service. Picking the lowest rate may not always be the right choice, as budget certainty only holds if the supplier can honor the number through the full term. Reach out to learn more about how to hedge your DASI exposure.